
Becoming a limited company director involves more than managing daily operations and making business decisions. Directors must also oversee company finances, maintain accurate records, understand their responsibilities, and meet applicable legal requirements.
Many limited company director mistakes begin with seemingly minor habits, such as mixing personal expenses with business payments, delaying bookkeeping, or overlooking important deadlines. Over time, these practices can create financial difficulties, reporting errors, and compliance problems.
The seven mistakes below explain what new directors should stop doing and how to establish better management practices. Although the principles apply internationally, specific legal and financial obligations vary by jurisdiction.
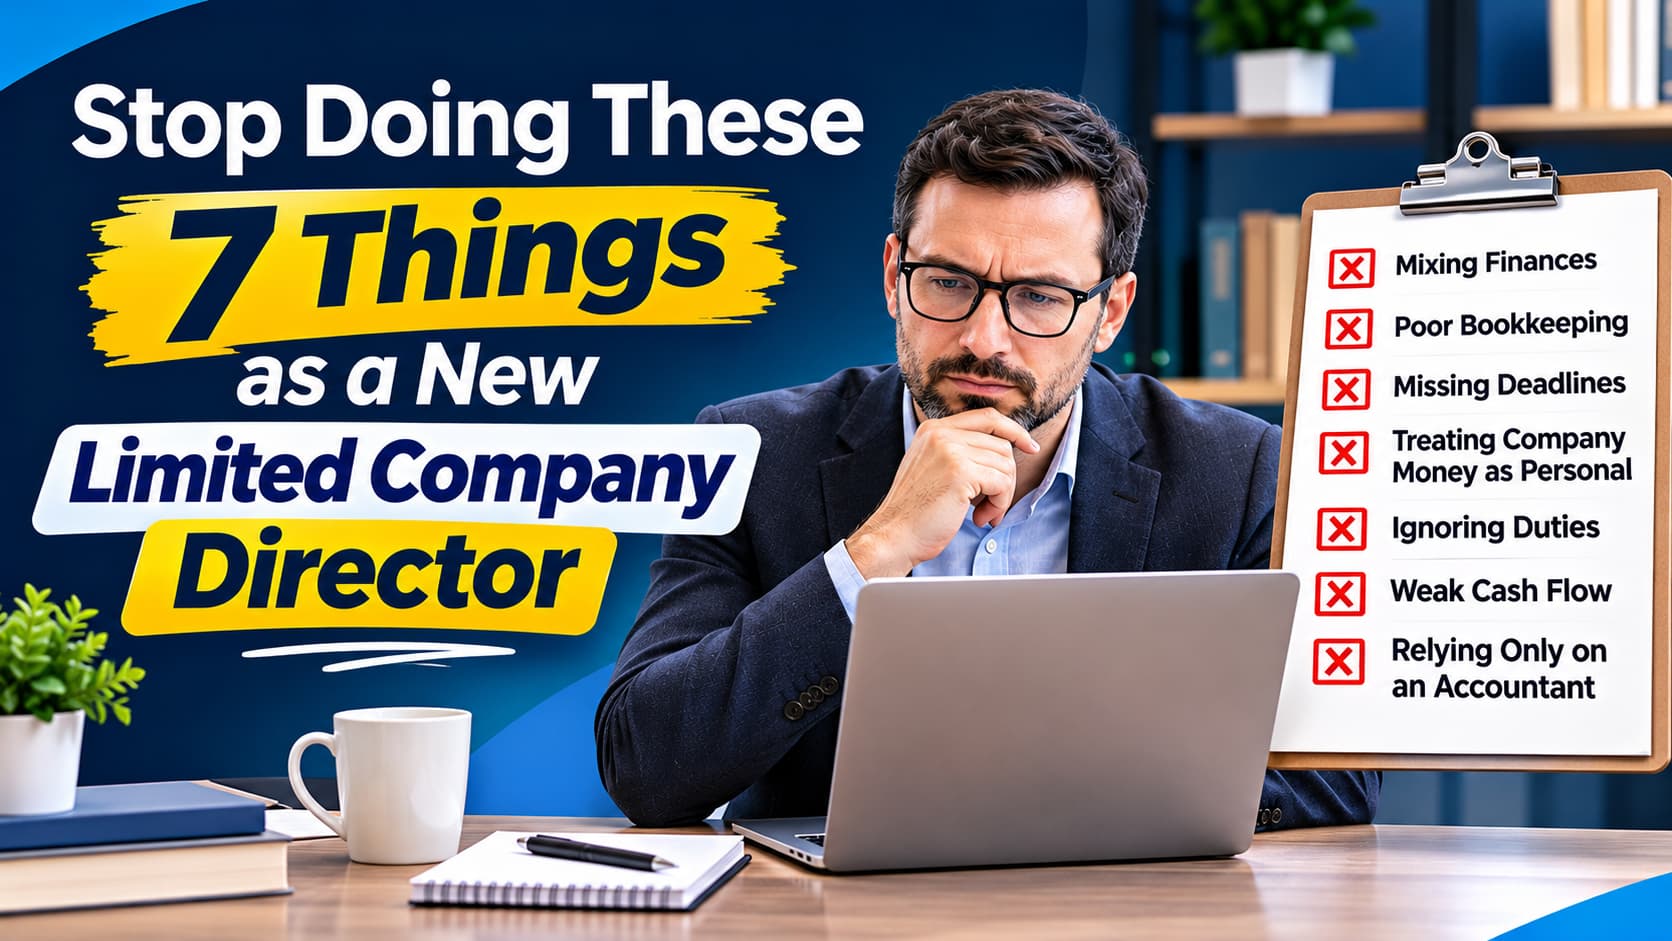
7 Common Mistakes New Limited Company Directors Should Avoid
| Mistake | Main Risk | What to Do Instead |
|---|---|---|
| 1. Mixing personal and company finances | Confusing financial records | Separate and document transactions |
| 2. Neglecting bookkeeping | Inaccurate financial information | Maintain updated records |
| 3. Ignoring compliance deadlines | Penalties and reporting problems | Use a compliance calendar |
| 4. Treating company money as personal income | Improper withdrawals | Follow permitted payment procedures |
| 5. Overlooking director responsibilities | Governance and legal risks | Understand applicable duties |
| 6. Ignoring cash flow | Difficulty meeting expenses | Forecast income and payments |
| 7. Relying entirely on accountants | Missed management responsibilities | Maintain financial oversight |
How We Identified These Common Director Mistakes
These seven mistakes were selected using established business management principles and publicly available guidance on corporate governance, accounting, financial recordkeeping, and regulatory compliance.
The selection prioritises problems that can affect newly incorporated businesses across different jurisdictions. Each mistake is evaluated according to its potential financial, administrative, operational, or legal consequences and the practical steps directors can take to reduce those risks.
The article provides general educational guidance rather than a ranking based on surveys or professional interviews. Country-specific legal requirements should always be verified with the appropriate authorities.
1. Stop Mixing Personal and Company Finances
Mixing personal spending with company transactions is a common mistake among first-time directors. Paying personal bills using company funds or covering business expenses without proper documentation can make financial records difficult to interpret.
This confusion may lead to inaccurate expense reporting, bookkeeping errors, and difficulties identifying the company’s actual financial position.
A limited company generally has a legal identity separate from its owners, although the exact implications depend on local company law.
Directors should maintain organised business accounts, keep transaction records, and document payments between themselves and the company.
Personal reimbursements, salaries, loans, and distributions may require different accounting treatments. Understanding these distinctions helps directors manage company funds responsibly without assuming that every personal-company transfer is prohibited.
2. Stop Neglecting Bookkeeping and Financial Records
Poor bookkeeping makes it difficult to understand how much money a company earns, spends, owes, or expects to receive.
When invoices, receipts, payments, and expenses are not recorded consistently, directors may make decisions using incomplete financial information.
Maintaining accurate bookkeeping helps businesses monitor expenditure, prepare financial reports, identify payment discrepancies, and organise information needed for taxation.
Directors should establish a regular recordkeeping routine rather than leaving financial administration until the end of a reporting period.
Suitable accounting software, organised digital documents, and periodic bank reconciliations can simplify this process.
Reviewing financial statements also helps directors identify unusual expenses, unpaid invoices, and emerging financial concerns before they become harder to manage.
3. Stop Ignoring Tax Obligations and Compliance Deadlines
Failing to monitor company reporting requirements can create unnecessary administrative and financial difficulties.
Depending on the jurisdiction, incorporated businesses may need to submit financial statements, tax returns, company updates, or other regulatory documents.
Missing applicable deadlines or providing inaccurate information may result in penalties, additional administrative work, or other consequences under local regulations.
A new limited company director should identify the company’s relevant reporting obligations soon after incorporation.
Maintaining a compliance calendar helps track important dates, document submissions, and regulatory notices.
Directors should also review communications from official authorities and confirm that required filings have been completed.
When requirements are unclear, qualified local accounting or legal advice can help establish an appropriate compliance process.
4. Stop Treating Company Money as Personal Income
Company revenue is not automatically personal income available for directors to spend.
Money received from customers may be needed to cover operating costs, employee payments, supplier invoices, taxes, and existing financial commitments.
Assuming that a healthy bank balance represents personal earnings can create liquidity problems and accounting complications.
This is one of the limited company director mistakes that can become particularly costly when withdrawals are poorly documented.
Depending on the company’s structure and applicable legislation, directors may receive compensation through salaries, dividends, expense reimbursements, or other permitted arrangements.
Director loans may also be subject to specific rules and reporting requirements.
Before withdrawing substantial funds, directors should understand the applicable treatment, document payments correctly, and consider professional accounting advice.
5. Stop Overlooking Your Responsibilities as a Company Director
Company directors have responsibilities that extend beyond supervising employees, securing customers, and developing business strategies.
Depending on applicable company law, director duties may involve acting in the company’s interests, exercising appropriate care, managing conflicts of interest, and maintaining proper oversight.
Ignoring these responsibilities can expose a business to governance problems, disputes, and potential legal consequences.
Directors should familiarise themselves with the legislation governing their company’s structure and place of incorporation.
Important decisions should be supported by appropriate information and documented when necessary.
It is also sensible to establish clear decision-making procedures and understand who has authority to approve significant transactions.
Responsible company management requires directors to consider financial consequences, legal obligations, and the interests protected by applicable law.
6. Stop Making Business Decisions Without Monitoring Cash Flow
A company can report a profit and still struggle to pay its bills.
Profit measures financial performance under applicable accounting principles, while cash flow reflects money entering and leaving the business.
For example, a company might complete a profitable project but receive customer payment several weeks later. Meanwhile, employee salaries, rent, and supplier invoices may become due.
Without sufficient available cash, the company could face payment difficulties despite recording strong sales.
Directors should prepare cash flow forecasts, review outstanding customer invoices, and monitor upcoming financial commitments.
Maintaining an appropriate financial reserve can also help businesses manage unexpected expenses.
Regular financial reviews support better budgeting, spending decisions, and realistic business planning.
7. Stop Assuming Your Accountant Handles Every Business Responsibility
Hiring an accountant does not automatically transfer every company responsibility away from its directors.
Accountants may support bookkeeping, financial reporting, tax preparation, and other agreed services. However, the exact division of responsibilities depends on the professional engagement and applicable laws.
Directors still need sufficient financial understanding to make informed business decisions and oversee important obligations.
Simply forwarding documents to an adviser without reviewing financial information can leave significant problems unnoticed.
Directors should regularly discuss financial reports, outstanding payments, tax considerations, and reporting deadlines with their advisers.
They should also understand which tasks have been delegated and which require direct management attention.
Professional support is most effective when directors remain informed, ask relevant questions, and maintain appropriate oversight.
How New Limited Company Directors Can Avoid Common Problems
Developing consistent management habits early can help directors reduce unnecessary financial and administrative problems.
Start by organising financial documents, establishing clear payment procedures, and reviewing business accounts regularly. Ensure company transactions are properly recorded and distinguish personal expenditure from legitimate business costs.
Directors should also introduce appropriate business automation where it can reduce repetitive administrative work, improve record organisation, or support routine financial processes.
Financial reviews should cover available cash, unpaid customer invoices, upcoming expenses, and significant business commitments.
Equally important is maintaining a calendar of applicable reporting obligations and understanding the company’s governance requirements.
Directors should seek qualified professional advice when facing unfamiliar financial, legal, or tax matters.
These practices help establish stronger oversight without unnecessarily complicating everyday company management.
Frequently Asked Questions
Q.1. What is the biggest mistake a new company director can make?
One of the most significant mistakes is failing to understand the company’s financial position and the director’s responsibilities. Poor financial oversight can contribute to cash shortages, inaccurate reporting, and compliance problems. New directors should establish organised financial procedures and understand their relevant obligations from the beginning.
Q.2. Can a company director use business money for personal expenses?
Directors cannot automatically treat company funds as personal money. However, certain payments or transfers may be permitted when properly authorised, documented, and accounted for under applicable laws. The treatment of salaries, dividends, reimbursements, and loans depends on the company’s legal structure and jurisdiction.
Q.3. Is a company director personally responsible for business debts?
Directors are not automatically personally liable for every debt owed by an incorporated company. However, personal liability may arise in specific circumstances, such as personal guarantees, certain unlawful conduct, or breaches of applicable legal duties. The circumstances and governing jurisdiction determine whether personal liability applies.
Final Thoughts
Avoiding common limited company director mistakes begins with understanding that company management requires financial discipline, accurate records, compliance awareness, and responsible decision-making.
Directors who separate personal and business finances, monitor cash flow, review financial information, and understand their obligations are better positioned to identify problems early.
Professional advisers can provide valuable support, but directors should remain actively involved in important business decisions.
Good management habits should be established from the beginning and reviewed as the company develops.
Consistent financial oversight and informed decision-making provide a practical foundation for responsible business operations.
Editorial Disclosure
This article provides general educational information about company management and director responsibilities. Any relevant commercial relationships associated with referenced services, websites, or providers should be disclosed by the publisher where applicable.
